A single hospital stay can wipe out months, sometimes years, of savings. That’s the blunt reality that pushes most people toward buying health insurance, usually right after a scare involving themselves or someone close to them. The problem is, by the time people actually look into it, they’re often confused by terms like sum insured, co-payment, and waiting period, all thrown at them at once.
This guide breaks health insurance down into plain language: what it actually covers, how the claim process works, and what to look for before you buy a policy.
What Is Health Insurance, in Simple Terms?
Health insurance is a contract where you pay a yearly premium to an insurer, and in return, the insurer covers your medical expenses up to a specified limit, called the sum insured, during that policy year. It’s designed to protect you from the financial shock of hospitalization, surgery, or serious illness, so you’re not paying entirely out of pocket when it matters most.
Most policies work on a reimbursement or cashless basis. In a cashless claim, the hospital bills the insurer directly if it’s part of the insurer’s network, and you don’t need to arrange large sums upfront. In a reimbursement claim, you pay the hospital first and submit bills to the insurer for repayment afterward.
What Does a Standard Health Insurance Policy Cover?
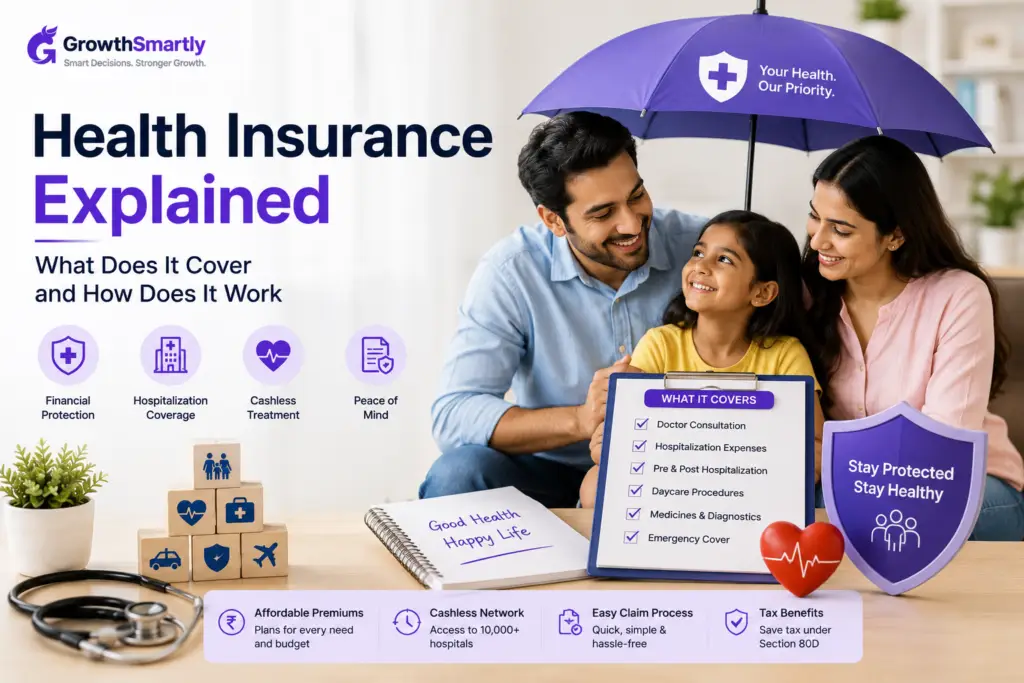
Coverage typically includes hospitalization expenses such as room rent, doctor’s fees, surgery costs, ICU charges, and nursing expenses. Most policies also cover expenses incurred a certain number of days before hospitalization and after discharge, commonly 30 to 60 days on either side, covering things like diagnostic tests, medicines, and follow-up consultations.
Many modern plans also include day care procedures that don’t require a 24-hour hospital stay, such as cataract surgery or certain chemotherapy sessions. Some policies extend to cover ambulance charges, organ donor expenses if you need a transplant, and even domiciliary treatment when hospitalization isn’t possible due to a lack of beds or the patient’s condition.
What’s Usually Not Covered
This is where a lot of policyholders get caught off guard at claim time. Most standard policies exclude cosmetic procedures, dental treatment unless caused by an accident, and pre-existing conditions during an initial waiting period, typically ranging from two to four years depending on the insurer and the condition. Pregnancy and childbirth are often excluded too, unless you’ve specifically opted for a maternity add-on or rider.
Self-inflicted injuries, treatment for substance abuse, and expenses arising from participation in adventure sports without proper disclosure are also commonly excluded. Reading the policy wording, particularly the exclusions section, matters far more than most buyers realize before they actually need to file a claim.
Understanding Waiting Periods
Nearly every health policy comes with waiting periods built in. There’s usually an initial waiting period of 30 days from policy start, during which most illnesses aren’t covered except accidents. Pre-existing diseases have a separate, longer waiting period before they become eligible for coverage. Certain conditions, like specific surgeries or treatments, may carry their own individual waiting periods too.
Understanding these timelines matters because buying a policy right before you anticipate needing treatment for a known condition won’t help. The waiting period exists precisely to prevent that kind of last-minute purchase.
Sum Insured and Co-payment: Getting the Terms Right
The sum insured is the maximum amount the insurer will pay in a policy year. Choosing this figure isn’t something to rush through; a sum that felt adequate five years ago may fall well short today given how quickly medical costs have risen, especially in metro cities.
Co-payment is a clause where you agree to bear a fixed percentage of every claim amount yourself, with the insurer covering the rest. Some policies, particularly those aimed at senior citizens, come with mandatory co-payment clauses. A lower co-payment percentage generally means a higher premium, so it’s a trade-off worth understanding rather than skipping over.
Individual Policy vs Family Floater
An individual policy covers one person with a dedicated sum insured just for them. A family floater covers multiple family members under a single sum insured that’s shared across everyone included. Floater plans are usually cheaper for covering a whole family, but the shared sum insured means a major claim by one member can significantly reduce what’s left for the others in that policy year.
Health insurance works best when you understand it before you need it, not while you’re standing at a hospital admission desk. Read the exclusions carefully, understand your waiting periods, choose a sum insured that reflects current medical costs rather than what felt sufficient years ago, and decide between individual and floater coverage based on your family’s actual health profile. A well-chosen policy turns a potential financial crisis into a manageable one.
Frequently Asked Questions
1. What is the difference between cashless and reimbursement claims?
In a cashless claim, the hospital bills the insurer directly if it’s part of the insurer’s network, so you don’t pay large amounts upfront. In a reimbursement claim, you pay the hospital yourself first and then submit bills to the insurer for repayment.
2. Does health insurance cover pre-existing conditions?
Pre-existing conditions are typically covered only after a waiting period, usually ranging from two to four years depending on the insurer and the specific condition. During this period, related medical expenses generally aren’t covered.
3. What is a family floater health insurance plan?
A family floater is a single policy that covers multiple family members using one shared sum insured, rather than separate coverage for each person. It’s usually more affordable than individual policies but means a large claim by one member reduces the amount available for others that year.
4. How much health insurance coverage should I buy?
There’s no fixed number, but many advisors suggest a sum insured that reflects current medical treatment costs in your city, factoring in inflation. Given how fast healthcare costs rise, revisiting your coverage every few years is a good habit.
5. Can I buy health insurance if I already have a medical condition?
Yes, but the condition will likely be treated as pre-existing and covered only after the applicable waiting period. Disclosing your medical history accurately during purchase is essential, since non-disclosure can lead to claim rejection later.