A gold loan is a secured loan in which a borrower pledges gold jewellery or coins with a bank or NBFC in exchange for funds, with the gold held as collateral until the loan is repaid. It is one of the fastest and most accessible ways to borrow money in India, especially for people who may not qualify easily for an unsecured personal loan.
If you’re considering unlocking the value of your gold instead of selling it — or comparing it with other ways to hold and use gold as an investment — understanding exactly how the loan process works, and where the risks lie, can help you make a more informed borrowing decision.
What Is a Gold Loan?
A gold loan lets you borrow money by pledging your gold ornaments, coins, or bars as security. The lender assesses the purity and weight of your gold, calculates its market value, and sanctions a loan amount based on a percentage of that value — known as the Loan-to-Value (LTV) ratio.
Unlike a personal loan, which is unsecured and depends heavily on your credit score and income proof, a gold loan is backed by a physical asset. This is why gold loans are usually quicker to approve, require less documentation, and are available even to people with a limited or poor credit history.
How Does a Gold Loan Work in India?
The gold loan process is fairly straightforward and typically follows these steps:
1. Gold Valuation The lender examines your gold for purity (usually 18 to 24 karat is accepted) and weighs it. Stones, beads, and other non-gold attachments are usually excluded from the valuation.
2. Loan Amount Calculation Based on the current market price of gold and the applicable LTV ratio (regulated by the RBI, generally up to 75% of the gold’s value for most lenders), the lender decides how much you can borrow.
3. Documentation and KYC You’ll need to submit basic KYC documents — proof of identity and address (Aadhaar, PAN, passport, voter ID, etc.). Income proof is usually not required.
4. Loan Sanction and Disbursal Once the gold is verified and paperwork is complete, the loan amount is disbursed — often within a few hours, and sometimes on the same day.
5. Safekeeping of Gold Your gold is stored securely by the lender, typically in insured, tamper-proof lockers, until the loan is fully repaid.
6. Repayment You repay the loan through EMIs, or through interest-only payments with a bullet repayment of the principal at the end, depending on the scheme you choose.
7. Gold Release Once the loan (principal and interest) is fully repaid, the lender returns your gold to you.
Gold Loan Eligibility and Documents Required
Gold loan eligibility criteria are generally simpler than most other loan types:
- Age: Usually 18 years and above
- Ownership: You must be the owner of the gold being pledged
- Documents: PAN card, Aadhaar card, or any other government-issued ID and address proof
- No income proof or credit score requirement in most cases, though some lenders may still check your credit history for higher loan amounts
This is one of the key reasons gold loans are popular among self-employed individuals, small business owners, farmers, and people without a formal salary structure.
How Much Loan Can You Get Against Gold?
The loan amount depends on:
- The current market price of gold
- The purity of your gold (24K gold gets a higher valuation than 18K or 22K)
- The weight of the gold, excluding stones and other embedded materials
- The lender’s applicable LTV ratio, which the RBI caps to manage risk for lenders and borrowers
For example, if your gold is valued at ₹5,00,000 and the lender offers an LTV of 75%, you could be eligible for a loan of up to ₹3,75,000. LTV ratios can vary between lenders and may also change based on RBI guidelines from time to time, so it’s worth checking the current applicable limit with your lender.
Gold Loan Interest Rates in India
Gold loan interest rates are generally lower than personal loan or credit card interest rates because the loan is secured. However, rates vary significantly based on the lender, loan tenure, and repayment scheme.
| Loan Type | Typical Interest Rate Range* | Collateral Required | Approval Speed |
|---|---|---|---|
| Gold Loan | Lower end, generally single digits to mid-teens | Yes (gold) | Same day to a few hours |
| Personal Loan | Usually higher than gold loans | No | 1–7 days |
| Credit Card Loan/EMI | Typically the highest | No | Instant, but costly |
*Interest rates change frequently based on RBI policy rates and lender-specific factors. Always check the latest rates directly with the bank or NBFC before applying, rather than relying on any fixed figure.
Gold Loan Repayment Options
Lenders usually offer more than one repayment structure, so you can choose what suits your cash flow:
- EMI-based repayment: Pay both principal and interest every month, similar to a regular loan
- Bullet repayment: Pay the entire principal and interest at the end of the tenure — useful for those expecting a lump sum later
- Interest-only payments: Pay interest monthly or quarterly, with the principal repaid at maturity
- Overdraft facility: Some lenders offer a gold loan overdraft, where you pay interest only on the amount you actually use, similar to a credit line
Choosing the right structure matters — a bullet repayment plan can be convenient short-term, but the total interest can add up if you delay repaying the principal.
Advantages of Taking a Gold Loan
- Quick disbursal, often within hours — similar in speed to an instant loan, but usually at a lower interest cost since it’s secured
- Minimal documentation — no income proof needed in most cases
- Lower interest rates compared to unsecured loans
- Flexible repayment options to match your cash flow
- No end-use restriction in most cases — funds can be used for medical needs, business, education, or emergencies
- Doesn’t require a strong credit score, making it accessible to more borrowers
Risks and Disadvantages of a Gold Loan
- Risk of losing your gold: If you default on repayment, the lender has the right to auction your pledged gold to recover the dues
- Gold price fluctuation: If gold prices fall sharply during the loan tenure, the lender may ask you to pledge additional gold or repay part of the loan (a margin call)
- Shorter tenures: Gold loans typically have shorter repayment periods (usually up to 3 years) compared to other secured loans
- Emotional value: Family jewellery often carries sentimental value beyond its market price, and the process of pledging it can feel like a bigger decision than it appears on paper
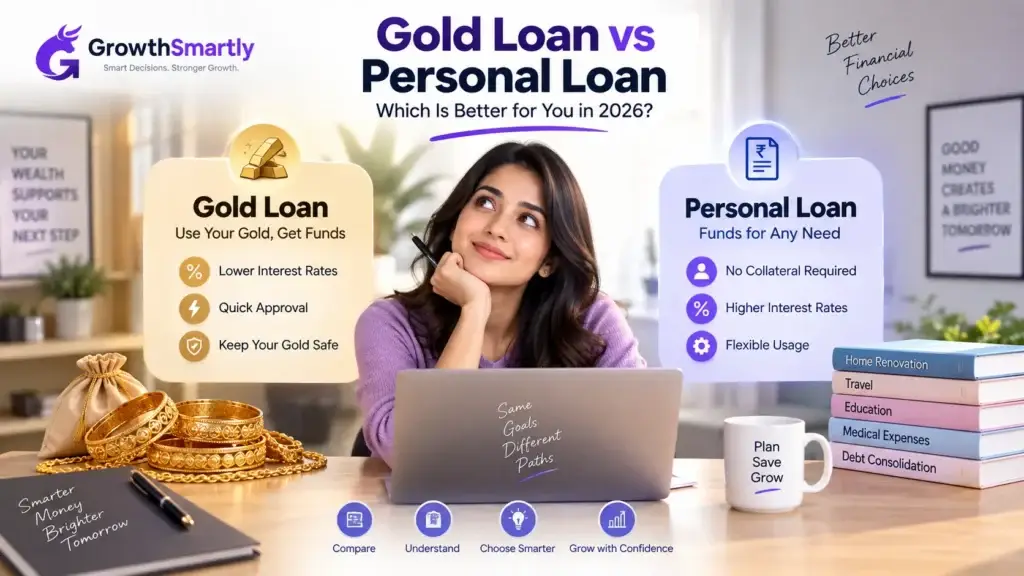
Gold Loan vs Personal Loan: Which Should You Choose?
| Factor | Gold Loan | Personal Loan |
|---|---|---|
| Collateral | Required (gold) | Not required |
| Interest Rate | Generally lower | Generally higher |
| Approval Time | Very fast | Moderate |
| Credit Score Impact | Less critical | Very important |
| Loan Amount | Based on gold value | Based on income and credit profile |
| Risk if Default | Gold can be auctioned | Credit score damage, legal recovery |
If you own gold and need funds quickly at a lower cost, a gold loan can be more efficient. If you don’t want to risk a physical asset and have a strong income and credit profile, a personal loan may offer more flexibility, even at a higher interest rate.
Is a Gold Loan a Good Option for You?
A gold loan can be a good option if:
- You need funds urgently and have idle gold jewellery or coins
- You want a lower interest rate than unsecured borrowing options
- You’re confident about repaying within the loan tenure
- You don’t have a strong credit history but still need access to credit
If your funding need is larger and long-term, it’s also worth comparing a gold loan with options like loan against property, which can offer higher loan amounts over longer tenures, though with a slower approval process.
It may not be the right choice if:
- You’re not confident about your ability to repay on time
- The gold holds significant sentimental or heirloom value you’re not comfortable risking
- You need a much larger loan amount than your gold’s value can support
As with any borrowing decision, it helps to compare the total cost (interest plus any processing charges) against alternatives, and to borrow only what you can comfortably repay.
Frequently Asked Questions
Can I get a gold loan without income proof?
Yes, most lenders do not ask for income proof for gold loans since the loan is secured against your gold. Basic KYC documents are usually sufficient.
What happens if I don’t repay my gold loan?
If you default on repayment, the lender has the right to auction the pledged gold to recover the outstanding amount after following the required notice process.
Is gold loan interest tax-deductible?
Interest paid on a gold loan may be eligible for tax benefits only if the loan is used for a specific purpose recognised under tax laws, such as for business or home construction/purchase. It’s advisable to check current income tax rules or consult a tax professional for your specific situation.
How is the value of my gold calculated?
Lenders typically value gold based on its purity and weight, using the prevailing market price of gold on the day of application. Stones and other non-gold materials are usually excluded from the valuation.
Can I take a gold loan on gold coins, not just jewellery?
Yes, most banks and NBFCs accept gold coins (usually up to a specified purity and weight limit) in addition to jewellery, though policies vary by lender.
How long does it take to get a gold loan approved?
Gold loans are among the fastest loan types to process, with many lenders disbursing funds within a few hours to a day, provided your documents and gold valuation are in order.
Explore more borrowing options and detailed guides on our Loans page.