A gold loan and a personal loan are both common ways to borrow money quickly in India, but they work very differently — a gold loan is secured against your gold, while a personal loan is unsecured and based on your income and credit profile. Choosing between them depends on what you have available (an asset vs a strong credit score), how urgently you need funds, and how much risk you’re comfortable taking on.
This guide compares both options across the factors that actually matter — cost, speed, eligibility, and risk — so you can decide which fits your situation better in 2026.
Quick Answer
If you own gold and want a lower-cost loan with fast approval, a gold loan is usually the more economical choice. If you don’t want to pledge an asset and have a stable income with a good credit score, a personal loan offers more flexibility, though typically at a higher interest cost.
What Is a Gold Loan?
A gold loan is a secured loan where you pledge gold jewellery, coins, or bars with a bank or NBFC in exchange for funds. The lender values your gold and sanctions a loan based on a percentage of its market value — known as the Loan-to-Value (LTV) ratio, which is capped by RBI guidelines. Since the loan is backed by a physical asset, approval is usually quick and doesn’t heavily depend on your credit score or income proof.
What Is a Personal Loan?
A personal loan is an unsecured loan, meaning no collateral is required. Lenders evaluate your income, employment stability, and credit score to decide your eligibility and the interest rate you’re offered. Because there’s no asset backing the loan, personal loans usually carry a higher interest rate and involve more documentation, including income proof and credit checks.
Gold Loan vs Personal Loan: Side-by-Side Comparison
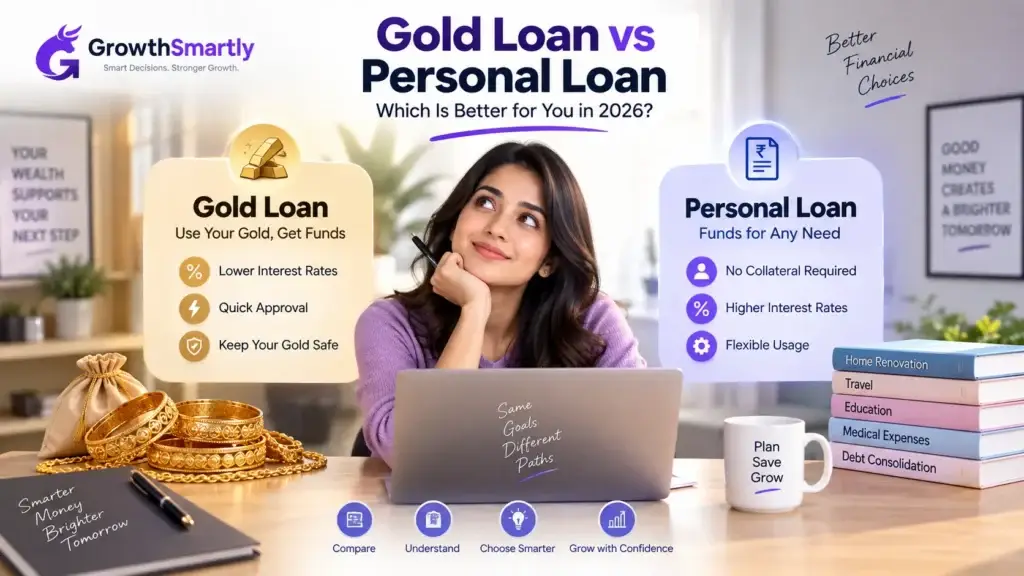
| Factor | Gold Loan | Personal Loan |
|---|---|---|
| Collateral | Required (gold jewellery/coins) | Not required |
| Interest Rate | Generally lower, since it’s secured | Generally higher, since it’s unsecured |
| Approval Time | Very fast — often same day | Moderate — typically 1–7 days |
| Documentation | Minimal (basic KYC) | More extensive (income proof, bank statements) |
| Credit Score Dependency | Low — approval possible even with a limited credit history | High — a strong score usually gets you better rates |
| Loan Amount | Based on gold’s market value and LTV ratio | Based on income, credit profile, and repayment capacity |
| Loan Tenure | Usually shorter (up to 3 years) | Can be longer (up to 5–7 years, depending on lender) |
| Risk if You Default | Lender can auction your pledged gold | Impact on credit score, legal recovery proceedings |
| End-Use Restrictions | Usually none | Usually none, though some lenders may ask the purpose |
Interest Rates: Which Costs Less?
Gold loans typically carry lower interest rates than personal loans because the lender’s risk is reduced by holding a physical asset as security. Personal loan rates depend heavily on your credit score, income stability, and existing relationship with the lender — a high credit score can narrow the gap, but a gold loan usually remains the cheaper option on a like-for-like basis.
That said, exact rates change frequently based on RBI’s policy rate and each lender’s internal risk assessment, so it’s important to compare current rates directly with banks or NBFCs rather than relying on last year’s figures. Once you have a rate in mind, you can use a loan EMI calculator to estimate your monthly repayment for either option.
Speed and Convenience: Which Is Faster?
Gold loans are generally faster to process since the lender’s main task is valuing your gold rather than verifying income documents. Many lenders disburse gold loan funds within a few hours.
Personal loans, especially from traditional banks, can take a few days as the lender verifies your income, employment, and credit history. Some digital lenders offer faster personal loan approvals, similar in speed to an instant loan, but usually at a higher cost than a gold loan.
Eligibility: Which Is Easier to Get?
- Gold loan: You mainly need to own gold and provide basic KYC documents. Income proof and credit score checks are often not required, making it accessible even if you’re self-employed, have irregular income, or a limited credit history.
- Personal loan: You typically need a stable income, a reasonably good credit score (usually 700+ for the best rates), and supporting documents like salary slips or bank statements.
If your credit score isn’t strong, a gold loan may be easier to qualify for than a personal loan.
Risk Factors to Consider
Gold Loan Risks
- If you fail to repay, the lender can auction your pledged gold after the required notice period
- A sharp fall in gold prices during the loan tenure may trigger a margin call, requiring you to pledge more gold or repay part of the loan early
- Sentimental value of family jewellery is a real, if non-financial, consideration
Personal Loan Risks
- Defaulting can seriously damage your credit score, affecting future borrowing
- Higher interest rates mean a bigger long-term repayment burden
- Some lenders charge higher processing fees and prepayment penalties
When Should You Choose a Gold Loan?
- You own gold that isn’t actively being used
- You need funds quickly and want a lower interest rate
- Your credit score isn’t strong enough for a competitive personal loan rate
- You’re confident about repaying within a relatively short tenure
When Should You Choose a Personal Loan?
- You don’t want to risk pledging a physical asset
- You have a stable income and a good credit score that qualifies you for a competitive rate
- You need a longer repayment tenure to keep EMIs manageable
- You’re consolidating multiple debts — in which case it’s worth comparing this against options like debt consolidation loans as well
Can You Use Both Strategically?
Some borrowers use a gold loan for short-term, urgent needs because of its speed and lower cost, while reserving a personal loan for larger or longer-term requirements where collateral isn’t available. The right mix depends on your specific financial situation, the amount you need, and how soon you can repay it.
Final Thoughts
Neither option is universally “better” — a gold loan tends to win on cost and speed if you have gold to pledge, while a personal loan offers flexibility without risking a physical asset. The right choice depends on your credit profile, urgency, and comfort with securing the loan against your gold. Compare the total cost, not just the interest rate, before deciding.
Explore more borrowing options and detailed guides on our Loans page.
Frequently Asked Questions
Which is cheaper, a gold loan or a personal loan?
A gold loan is usually cheaper because it’s secured against your gold, which reduces the lender’s risk. Personal loans, being unsecured, generally carry higher interest rates.
Does a gold loan affect my credit score?
Yes, a gold loan is typically reported to credit bureaus, and timely repayment can help build your credit history, just like any other loan. Missed payments can negatively affect your score.
Can I get a personal loan if I have a low credit score?
It’s possible, but you’ll likely be offered a higher interest rate, or your application may be rejected by some lenders. A gold loan can be a more accessible option in this situation if you own gold.
Which loan is better for a medical emergency?
For urgent situations, a gold loan is often preferred due to faster disbursal and lower interest rates, provided you have gold available to pledge. If not, a personal loan or instant loan option can still help you access funds quickly.
Is it safe to pledge gold with a bank or NBFC?
Reputed banks and NBFCs store pledged gold in secure, insured lockers and follow RBI-regulated processes. It’s advisable to choose a well-established, regulated lender and keep your loan documents and receipts safe.
Can I switch from a personal loan to a gold loan later?
You can technically close a personal loan (subject to foreclosure terms) and take a gold loan separately if it works out cheaper, but it’s worth calculating any prepayment charges on the personal loan before switching.