The gold loan amount you can get for 10, 20 or 50 grams of gold depends on three things: the purity of your gold, the prevailing market price on the day of valuation, and the Loan-to-Value (LTV) ratio your lender applies — which is capped at 75% under RBI guidelines. There’s no single fixed number, since gold prices change daily, but you can estimate your eligible loan amount fairly closely once you know these three inputs.
This guide breaks down exactly how the calculation works and gives you a worked example so you can estimate your own eligible amount before visiting a lender.
Quick Answer: The Formula
Eligible Loan Amount = (Net Gold Weight × Gold Price per Gram) × LTV Ratio
The “net gold weight” excludes stones, beads, and other non-gold materials attached to your jewellery — only the actual gold content is valued.
What Determines Your Gold Loan Amount?
1. Purity of Your Gold Gold jewellery in India is commonly 18K, 22K or 24K. Higher purity gold is valued higher per gram, so 22K jewellery will fetch a higher loan value than an equivalent weight of 18K jewellery.
2. Net Gold Weight Lenders typically deduct the weight of stones, meenakari work, or other embellishments before valuing your gold, since these do not count as gold content. This means the loan amount is based on your jewellery’s actual gold weight, not its total weight as sold.
3. Reference Gold Price Lenders use a reference price (often based on the prevailing market rate for 22K gold) to value your pledged gold. This price moves daily along with the broader gold market, so the same jewellery could fetch a different loan amount depending on when you apply.
4. LTV Ratio The Loan-to-Value ratio determines what percentage of your gold’s assessed value you can actually borrow. RBI caps this at 75% for most gold loans, though individual lenders may offer a lower ratio depending on the loan amount, scheme, or your relationship with the lender.
Worked Example: 10g, 20g and 50g of Gold
To illustrate the calculation, here’s an example using an approximate 22K gold rate of around ₹14,100 per gram (as seen in mid-September 2026). Remember, this rate changes daily, so treat these figures as illustrative rather than exact.
| Gold Weight | Approx. Gold Value (22K) | Loan at 75% LTV | Loan at 60% LTV (conservative estimate) |
|---|---|---|---|
| 10 grams | ₹1,41,000 | ~₹1,05,750 | ~₹84,600 |
| 20 grams | ₹2,82,000 | ~₹2,11,500 | ~₹1,69,200 |
| 50 grams | ₹7,05,000 | ~₹5,28,750 | ~₹4,23,000 |
These figures assume the full weight is 22K gold with no stones or other deductions. If your jewellery has embedded stones or is a lower purity like 18K, your eligible loan amount will be lower than shown here.
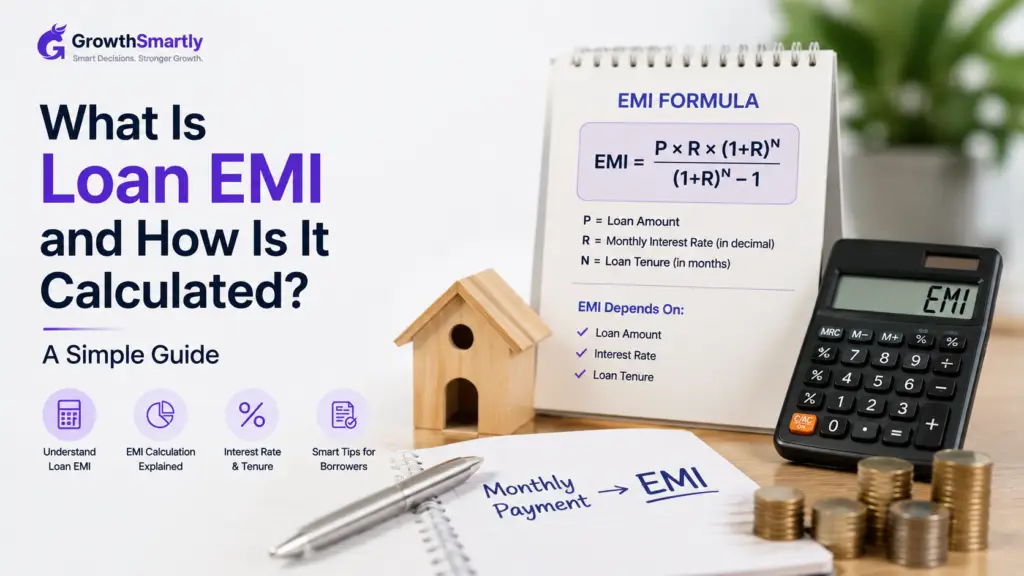
To check what you could get based on today’s gold price, use a loan EMI calculator once you have your estimated loan amount, so you also know what your monthly repayment might look like.
Why Your Actual Offer May Differ From the Calculation
- Stones and embellishments: A necklace with heavy stone work will have a lower “net gold weight” than its total weight suggests
- Purity assumptions: If your jewellery is actually 18K rather than 22K, the per-gram value used will be lower
- Lender-specific LTV: Not all lenders offer the maximum 75% LTV on every scheme — some cap it lower for larger loan amounts or specific products
- Valuation method: Lenders may use slightly different reference prices or rounding methods, leading to small variations between offers
- Additional charges: Processing fees or valuation charges may be deducted from the disbursed amount, even if they don’t change the sanctioned loan figure
How to Estimate Your Own Gold Loan Amount
- Weigh your gold jewellery and separate the approximate gold weight from stones or other materials, if any
- Check the current 22K (or applicable purity) gold rate for the day
- Multiply your net gold weight by the current price per gram to get the approximate gold value
- Apply the LTV ratio your chosen lender offers (ask this upfront, as it varies) to estimate your eligible loan amount
This gives you a realistic estimate to compare against the actual offer a lender gives you after their own valuation.
Does More Gold Always Mean a Proportionally Higher Loan?
Generally yes — the loan amount scales roughly in proportion to your gold’s value, since the LTV ratio is applied as a percentage. However, some lenders may apply slightly different LTV slabs depending on the total loan amount, so it’s worth checking whether a larger pledge qualifies for the same LTV percentage as a smaller one. It’s also worth comparing this option with a gold loan guide that covers valuation and LTV in more depth before pledging a larger quantity of gold.
Final Thoughts
The exact gold loan amount for 10, 20 or 50 grams isn’t a fixed number — it moves with the gold market and depends on your jewellery’s purity and the lender’s LTV policy. Use the formula above to get a reasonable estimate before you visit a lender, but always confirm the final valuation and offer directly, since small differences in purity assumptions or reference prices can change the final amount. If you’re also weighing other borrowing options, it’s worth comparing this against a personal loan to see which suits your situation better.
Explore more borrowing guides on our Loans page.
Frequently Asked Questions
How much loan can I get for 10 grams of gold?
The amount depends on the purity, purity-adjusted weight, and the current gold price, along with the lender’s LTV ratio. Using an illustrative 22K rate and 75% LTV, 10 grams could fetch roughly ₹1,00,000–1,10,000, though this varies with the daily gold price and lender policy.
Does the loan amount change if my gold is 18K instead of 22K?
Yes. Lower-purity gold has a lower per-gram value, so 18K jewellery of the same weight will typically fetch a smaller loan amount than 22K gold.
Are stones and gemstones included in the gold valuation?
No, most lenders exclude the weight of stones, beads, and other non-gold materials when calculating your loan amount, since only the actual gold content is valued.
Is the LTV ratio the same for all gold loan amounts?
Not always. While RBI caps the maximum LTV at 75% for most gold loans, individual lenders may apply a lower ratio for certain loan amounts or schemes, so it’s worth confirming the applicable LTV before applying.
Can I get a higher loan amount by pledging more gold?
Generally, yes — the loan amount increases roughly in proportion to the additional gold value pledged, subject to the applicable LTV ratio and any lender-specific caps on maximum loan amount.
How often does the gold price used for valuation change?
Gold prices can change daily based on domestic and international market movements, so the loan amount you’re offered can differ from one day to the next, even for the same quantity and purity of gold.