If you cannot repay a gold loan, the lender does not seize your gold immediately — RBI-regulated norms require the bank or NBFC to send you a formal notice and a defined window to clear your dues before your pledged gold can be auctioned. Understanding this process, along with your rights as a borrower, can help you avoid losing your gold unnecessarily and act quickly if repayment becomes difficult.
This guide explains what actually happens after a missed gold loan payment, how the auction process works, and practical steps you can take before it gets to that stage.
Quick Answer: What Happens After You Miss a Gold Loan Payment?
- The lender sends reminders and applies penal or overdue charges as per your loan agreement
- If dues remain unpaid for an extended period, your account may be classified as overdue or a non-performing asset
- The lender issues a formal written auction notice, giving you a defined notice period to repay
- If you still don’t repay within that window, the lender can auction your pledged gold to recover the outstanding amount
- Any surplus from the auction, after deducting dues and charges, is required to be returned to you
Step-by-Step: From Missed Payment to Auction
1. Grace Period and Reminders
Most lenders don’t act immediately after a single missed payment. You’ll typically receive reminder calls, SMS alerts, or emails asking you to clear the overdue amount. RBI does not mandate a uniform grace period across all lenders, but fair practice norms require lenders to communicate clearly before escalating recovery action.
2. Overdue and Penal Charges
Once a payment is missed, penal or overdue interest charges usually apply, as disclosed in your loan agreement and Key Facts Statement (KFS). These charges add to your outstanding balance the longer the loan remains unpaid.
3. Formal Auction Notice
If dues remain unpaid beyond the lender’s internal timeline, the lender is required to issue a formal written notice before auctioning your gold. Under RBI’s tightened 2026 gold loan directions, lenders must give you meaningful advance notice — commonly cited in the range of 14 to 30 days depending on the specific lender policy and loan agreement — clearly stating the amount due, the auction date, and how you can still repay to stop the process. It’s important to check your specific loan agreement and KFS for the exact notice period that applies to your loan.
4. The Auction Itself
If you don’t clear your dues within the notice period, the lender can proceed with a public auction of your pledged gold. RBI’s updated norms require:
- A minimum reserve (floor) price, generally not below roughly 85–90% of the current market value of the gold, to prevent undervaluation
- Valuation aligned with a standard reference rate (such as IBJA-published rates), rather than an arbitrary internal price
- Transparent, publicly announced auctions, rather than private or opaque sales
5. Settlement of Proceeds
After the auction, the lender recovers the outstanding principal, interest, and applicable charges from the sale proceeds. If the gold sells for more than what you owe, the surplus must be returned to you — the lender cannot keep the excess amount.
What If the Gold Loan Isn’t Fully Paid Off Even After Auction?
In rare cases where the auction proceeds don’t fully cover your outstanding dues (for example, if gold prices have fallen sharply), you may still be liable for the shortfall, depending on your loan agreement. This is one reason it’s worth monitoring gold price movements if you’re carrying a large gold loan for an extended period.
Your Rights as a Borrower Facing Default
- Right to advance notice: You cannot be auctioned without proper written notice
- Right to fair valuation: The auction reserve price must reflect a fair, standardised gold rate, not an arbitrary low figure
- Right to the surplus: Any amount left over after your dues are cleared must be returned to you
- Right to repay and stop the auction: You can typically clear your dues at any point before the auction actually takes place to reclaim your gold
- Right to a clear disclosure: Lenders are required to clearly disclose interest rates, charges, and the consequences of default upfront in your loan agreement
How to Avoid Losing Your Gold
- Borrow only what you genuinely need. A smaller loan is easier to repay comfortably within the tenure.
- Choose a repayment scheme you can actually manage. If you’re unsure about consistent monthly cash flow, a bullet repayment plan might suit you better than an EMI structure, or vice versa — match the scheme to your income pattern.
- Track your due dates. Set reminders well before your EMI or interest payment date to avoid accidental defaults.
- Talk to your lender early if you’re struggling. Many lenders offer partial payment options, renewal, or restructuring if you reach out before the account becomes seriously overdue — waiting until the auction notice stage limits your options.
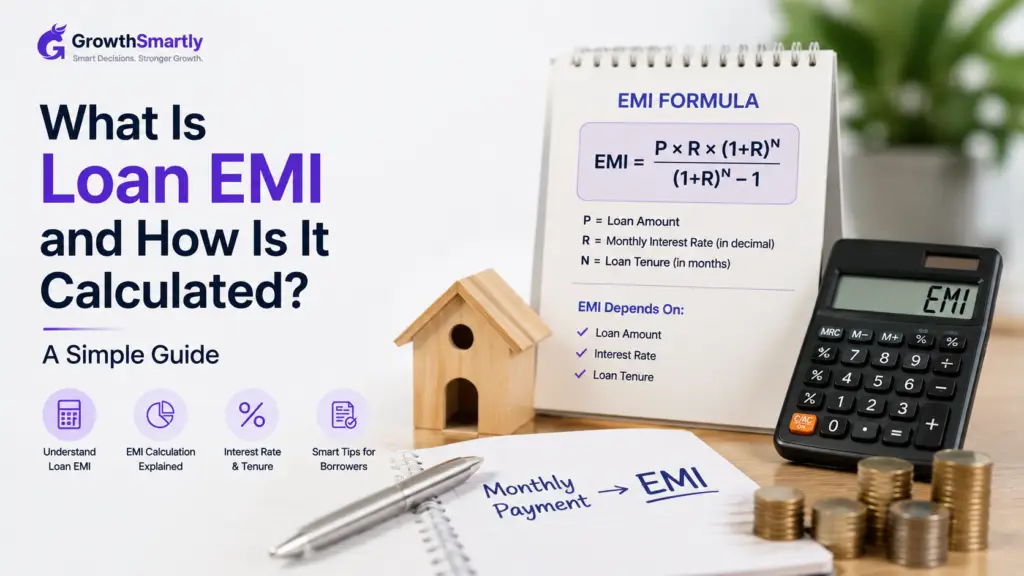
- Use an EMI calculator before borrowing. A loan EMI calculator can help you check whether the repayment amount actually fits your monthly budget before you take the loan.
- Consider your alternatives if you’re already stretched. If you’re juggling multiple debts, it may be worth exploring debt consolidation options rather than letting several loans go into default at once.
- Keep your contact details updated with the lender. Missed notices due to an outdated phone number or address can accelerate the process without your knowledge.
Final Thoughts
A gold loan default doesn’t mean instant loss of your jewellery — RBI’s borrower protection norms build in notice periods, fair valuation rules, and a right to any surplus from the auction. That said, the best strategy is to avoid reaching this stage altogether: borrow an amount you’re confident you can repay, track your due dates, and speak to your lender the moment repayment starts to feel difficult.
Explore our detailed gold loan guide to understand valuation and LTV before borrowing, or browse more loan guides on GrowthSmartly.
Frequently Asked Questions
Can a lender auction my gold immediately after one missed payment?
No. Lenders are required to follow a structured process involving reminders, overdue charges, and a formal written notice period before any auction can take place. A single missed payment does not trigger an immediate auction.
How much advance notice must a lender give before auctioning gold?
Under RBI’s tightened gold loan norms, lenders must provide meaningful advance written notice, commonly cited in the range of 14 to 30 days depending on the lender’s specific policy. Always check your loan agreement or Key Facts Statement for the exact period that applies to you.
Will I get any money back if my gold sells for more than I owe?
Yes. If the auction proceeds exceed your outstanding dues, including interest and charges, the surplus amount must be returned to you as per RBI’s borrower protection norms.
Can I stop the auction by repaying just before the auction date?
In most cases, yes — you can typically repay your outstanding dues and reclaim your gold any time before the actual auction takes place, though it’s best to confirm the exact cut-off with your lender.
What happens if the auction doesn’t cover my full outstanding amount?
If gold prices have fallen or the auction proceeds are insufficient to cover your dues, you may remain liable for the shortfall, depending on the terms of your loan agreement.
Does defaulting on a gold loan affect my credit score?
Yes, in most cases. Gold loans are usually reported to credit bureaus, so missed payments and default can affect your credit history, even though the loan itself is secured against your gold.